Mortgages for People With Bad Credit in the UK: Understanding Your Options in 2026

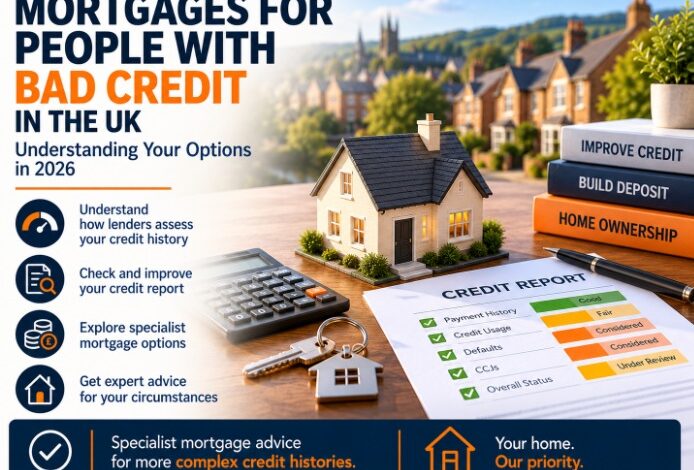
Previous financial difficulties can make applying for a mortgage feel intimidating. Missed payments, defaults, county court judgments or a history of high borrowing may affect how lenders assess an application. However, bad credit does not automatically mean that homeownership is impossible.
The options available depend on the nature of the credit problem, how long ago it occurred, whether outstanding debts have been resolved and the applicant’s current financial position. Understanding these factors can help borrowers prepare realistically and avoid unnecessary setbacks.
What Is Adverse Credit?
Adverse credit is a general term for information in a credit history that may make lenders view an application as higher risk.
Examples include missed credit-card or loan payments, defaults, county court judgments (CCJs), individual voluntary arrangements, bankruptcy and substantial unsecured borrowing.
Different lenders apply different criteria. A recent missed payment may be treated differently from a historic default that has been settled for several years. A lender may also consider whether a financial problem arose from a temporary event or reflects an ongoing difficulty managing commitments.
There is no single credit score or universal rule that determines whether an applicant can obtain a mortgage. Lenders use their own assessment processes, and the overall application matters.
Check Your Credit Reports First
Before applying, obtain copies of your credit reports and review the information carefully.
Look for incorrect balances, accounts that do not belong to you, outdated addresses and missed payments that have been recorded incorrectly. If you identify an error, contact the relevant credit reference agency and the organisation that supplied the information.
Do not assume that paying a debt automatically removes accurate negative information from your credit report. Different types of records have different reporting periods and rules.
If a debt remains outstanding, establish the amount owed and understand the available repayment options. Where appropriate, seek independent debt advice before taking on additional borrowing.
Correcting genuine errors and understanding your current position can help you make a more informed decision about when to apply.
How Lenders Assess Applicants With Bad Credit
Lenders consider the severity and timing of credit problems alongside income, deposit size, employment, existing commitments and the property’s value.
For example, an applicant with a historic, settled default and stable income may have different options from someone with several recent missed payments and significant outstanding debt.
The deposit can also affect the products available. A larger deposit reduces the loan-to-value ratio and may help with eligibility, although it does not automatically overcome every credit issue.
Some lenders specialise in applicants with more complicated credit histories. Their products may involve higher interest rates, additional fees or stricter conditions. It is important to compare the total cost and not focus solely on whether a lender is willing to consider the application.
Approval should never be assumed before a lender has reviewed the circumstances and supporting documents.
Practical Steps to Strengthen Your Application
There are several ways to improve your financial preparation.
Make payments on time. Consistent payment behaviour can help demonstrate improved financial management. Set up reminders or suitable payment arrangements where possible.
Reduce existing debt. Lower outstanding balances may improve affordability, depending on the lender’s calculations and your overall circumstances.
Avoid unnecessary credit applications. Multiple applications in a short period can complicate your credit profile. Apply only when you have a reasonable understanding of your eligibility.
Build a sustainable deposit. A deposit can improve the loan-to-value ratio, but keep enough money for legal fees, moving expenses and emergencies.
Maintain clear financial records. Lenders may request payslips, bank statements, evidence of deposit funds and explanations for particular transactions.
Be transparent. Disclose relevant financial commitments accurately. Hiding debt or providing misleading information can damage an application and may have serious consequences.
These measures do not guarantee a mortgage, but they can help create a clearer picture of your circumstances.
Should You Use a Specialist Mortgage Adviser?
Adverse-credit cases can be more complicated because lenders differ in their rules regarding defaults, CCJs, debt arrangements and previous insolvency.
A mortgage adviser may help identify lenders whose published criteria are relevant to your circumstances, explain the documentation required and discuss the potential costs of specialist borrowing.
Before proceeding, ask whether the adviser can access the relevant lenders, how the adviser is paid and whether an initial discussion carries a fee. Also establish whether any lender recommendation is based on a full assessment of your circumstances.
Prestige Mortgage Solutions Ltd advertises mortgage support for borrowers with complex financial circumstances, alongside residential mortgages and remortgages.
A firm’s advertised specialism is not a guarantee that it can arrange a mortgage for every applicant. Confirm the current regulatory status and permissions of the firm through the Financial Conduct Authority’s register
Understand the Cost of Specialist Mortgages
A mortgage offered to someone with adverse credit may have a higher interest rate or additional fees than a standard product.
Compare the monthly payment, product fee, valuation costs, early repayment charges and the total cost over the relevant period. Consider what will happen when the initial rate ends and whether the mortgage could become difficult to afford if rates rise.
Do not accept a product simply because it is the first offer available. If the cost is unaffordable, it may be better to improve your financial position and reassess your options later.
Be cautious of anyone who promises guaranteed mortgage approval, asks for misleading information to be supplied to a lender or pressures you to pay unexplained upfront charges.
How the Mortgage Market Is Changing in 2026
The UK mortgage market remains sensitive to interest-rate expectations and economic uncertainty. Bank Rate stood at 3.75% following the Bank of England’s September 2026 decision, while mortgage pricing came under renewed pressure during October.
The Financial Conduct Authority announced proposals in June 2026 aimed at helping more people access mortgages. The proposals included greater flexibility for lenders when considering individual circumstances and certain past or minor credit-history issues.
These proposals are not a guarantee that a borrower with adverse credit will qualify, nor should they be interpreted as a universal change to every lender’s policy. Applicants should check the current regulatory position and each lender’s eligibility criteria.
Consider Whether Buying Now Is the Right Decision
Securing a mortgage should not be the only objective. The repayments must be sustainable, and homeownership brings additional costs that can be difficult to manage when finances are already under pressure.
Before applying, prepare a realistic household budget and consider whether you could afford repairs, insurance, bills and mortgage payments during an unexpected drop in income.
If existing debts are causing financial difficulty, independent debt advice may be more appropriate than taking on a mortgage immediately. Converting unsecured debts into borrowing secured against a home can increase the consequences of non-payment.
Final Thoughts
A difficult credit history can reduce mortgage options, but it does not automatically close every door. The key is to understand the information lenders will see, address errors, manage existing commitments and identify products that fit your current circumstances. Contact us now.
Careful preparation and appropriate professional guidance can help borrowers make informed decisions without relying on unrealistic promises. The right timing matters just as much as finding a lender willing to consider an application.
This article is for general information only and does not constitute mortgage, debt, legal or financial advice. Specialist mortgage products may cost more and are not guaranteed to be available. Your home may be repossessed if you do not keep up repayments on your mortgage.
